
Disability insurance in Canada: what happens if illness or injury stops the paycheque?
Disability insurance replaces part of your income when a covered illness or injury keeps you from working. The gaps are usually in the fine print of your group plan.
Pankaj helps employees review group LTD, and helps self-employed people and professionals look at individual income protection, in Ontario, Alberta, British Columbia, Manitoba, Saskatchewan, New Brunswick and Nova Scotia.
In short
Disability insurance pays a monthly income if illness or injury stops you from working. FCAC says it generally replaces 60% to 85% of income, up to plan maximums. Benefits start after a waiting period (often 30 to 120 days) and last for the benefit period. They are tax-free if you pay the whole premium and taxable if your employer pays any of it.
How big is your income-protection gap?
A quick check of how long your savings would last. It doesn't quote insurance. No data leaves this page.
For cash-flow planning only. Not a quote, recommendation or underwriting decision. For a full analysis, use the disability insurance calculator.
Your ability to earn may be your largest asset
Rent or the mortgage, groceries, the car, childcare, debt payments and savings plans all keep going when your paycheque stops. Disability insurance moves part of that risk to an insurer.
FCAC says disability insurance generally replaces 60% to 85% of income, up to plan maximums. The money starts only after the waiting period, and only if the claim meets the policy definition. The financial hit can begin weeks before the first cheque.
Government benefits help less than people expect. EI sickness benefits pay up to 26 weeks at 55% of earnings, to a maximum of $729 a week. Beyond that, you rely on group or individual coverage and savings.
Numbers to know
- 60% to 85%
- Income disability insurance generally replaces (FCAC)
- 60% to 70%
- What most LTD plans replace
- Up to 6 months
- Typical short-term disability benefits
- 2 years
- When many plans switch to an "any job" test
- 26 weeks
- Maximum EI sickness benefits, at 55% up to $729 a week
Six terms that matter more than the premium
Monthly benefit
The most the contract pays each month, subject to income rules and offsets from other disability income.
Waiting period
How many days you must be disabled before benefits start. Match it to your emergency savings.
Benefit period
How long benefits can continue for one disability, as long as you keep meeting the claim requirements.
Definition of disability
The test of whether you count as disabled. It decides more claims than any other clause.
Partial or residual
Some contracts pay when you can work only part-time or your income drops, not just when you can't work at all.
Exclusions
Every policy limits coverage somewhere. The full contract, not a marketing summary, controls the claim.
Short-term vs long-term disability
FCAC describes short-term coverage as typically paying for up to 6 months. Long-term disability generally starts when short-term disability, sick leave or EI sickness benefits end.
| Feature | Short-term disability | Long-term disability |
|---|---|---|
| Main role | Covers the early months of a disability | Covers longer disabilities that continue |
| Common source | Usually an employer plan or sick-leave policy | Employer plan or an individual policy |
| How long | Typically up to 6 months | Can run for years, subject to the policy terms |
| Check | Waiting period, how it works with sick leave and EI, tax | Definition of disability, monthly maximum, offsets, benefit period, portability |
Employer plan vs individual policy
Having LTD at work doesn't mean all of your income is protected.
| Question | Employer / group plan | Individual disability policy |
|---|---|---|
| Who controls it? | The employer chooses and can change the plan | You own it, under its contract terms |
| Does it follow you? | Usually ends when the job or eligibility ends | Stays in force while you pay the premiums |
| Monthly benefit | Set by a formula, often with a monthly maximum | Based on your income, occupation, other coverage and underwriting |
| Tax | Taxable if the employer pays any of the premium | Tax-free if you pay the whole premium yourself |
| Definition of disability | Set by the group contract | Chosen from the insurer's options, if you qualify |
| First step | Get the booklet and the monthly maximum | Compare the contract with your uncovered gap |
Practical tip: before buying more coverage, ask HR for your group disability booklet or benefits certificate. Check the benefit formula, monthly maximum, waiting period, benefit period, tax treatment, offsets, portability and definition of disability.
"Own occupation" is not a universal promise
Contracts use different tests, and many change the test after a set period. Labels such as own occupation, regular occupation or any occupation mean nothing until you read the definition behind them.
For physicians, dentists, lawyers, accountants, executives and skilled trades, the wording matters most. Being able to do some other job may not replace the income of the job you trained for.
Ask these questions of any policy:
- How does it define total disability?
- Does the definition change after 2 years or another period?
- What happens to benefits if you work in another occupation?
- Is partial or residual disability covered?
- Is there an income-loss requirement?
- What are the exclusions and optional riders?
Who usually has a bigger gap?
- Self-employed Canadians: no employer LTD and no sick leave. Personal savings, business cash flow and individual coverage have to be planned together.
- Professionals: specialized duties make the definition of disability central.
- Business owners: personal income and business expenses are separate risks. Business overhead expense coverage helps pay eligible business costs, not your own income.
- Commissioned employees: group plans may not count commissions or bonuses.
- High earners: group monthly maximums can leave a large share of income uninsured.
- Single-income households: one paycheque carries everything.
What affects disability insurance premiums?
There is no one monthly price. A quote depends on you and the contract:
- Age when you apply
- Occupation: physical duties and hazards set the occupation class
- Health history: may bring exclusions, ratings or a lower benefit
- Monthly benefit: a larger benefit costs more, within income limits
- Waiting period: longer waits cost less
- Benefit period and features: longer periods and extra riders cost more
What decides whether a claim is paid?
- The policy definition. A diagnosis alone doesn't decide it; the disability must meet the contract's test.
- The waiting period must be satisfied first.
- Exclusions and pre-existing condition clauses.
- Proof of income, especially for self-employed people and variable pay.
- Medical evidence of how the condition limits your work.
- Other disability income that may be offset against the benefit.
How to review your coverage
Start with the risk you already have, not a product brochure.
- Add up essential monthly expensesThe minimum your household needs each month.
- Review your employer coverageGet the LTD booklet, the monthly maximum and who pays the premium.
- Check your savingsHow long they would cover the waiting period and the monthly gap.
- Compare contract wordingOccupation definition, benefit period, residual benefits, exclusions and offsets.
- Apply for a suitable amountThe benefit you get is subject to financial and medical underwriting.
Bring your group benefits booklet or existing policy to a call with Pankaj. He will go through the gap, the waiting period, the benefit period and the definitions with you. Related: critical illness insurance, which pays a lump sum on diagnosis rather than a monthly income.
Disability insurance in Canada: common questions
What is disability insurance?
Disability insurance pays you a monthly income if an illness or injury stops you from working, subject to the policy's definition of disability, waiting period, benefit period and exclusions.
Its job is to replace part of the paycheque you would otherwise lose while you can't work.
How much of my income can disability insurance replace in Canada?
The Financial Consumer Agency of Canada says disability insurance generally replaces between 60% and 85% of your income, up to plan maximums.
Most long-term disability plans replace 60% to 70% of normal income. What you can buy depends on your income, occupation, existing coverage and underwriting.
Do I need individual disability insurance if I have LTD at work?
Not necessarily, but review the group plan first. Check the monthly maximum, whether benefits are taxable, the waiting period, the benefit period, offsets and the definition of disability.
Individual coverage makes sense when a real gap remains, or when you want coverage that stays with you if you change jobs.
What is a waiting or elimination period?
It is the time you must be disabled before benefits start, for example 30, 60, 90 or 120 days.
A longer waiting period lowers the premium but means your savings must carry you longer. Use the gap checker to see how much cash that takes.
What is the benefit period?
The longest time benefits can be paid for one disability, for example 2 years, 5 years or to a set age.
Benefits still depend on meeting the policy definition throughout the claim.
What does own occupation mean?
Own-occupation wording pays if you can't do the main duties of your own job, even if you could do other work.
Many plans switch to a stricter "any occupation" test after a set period, often 2 years. FCAC notes that after 2 years you may keep receiving benefits only if you can't do any job. Read the exact wording.
Are disability insurance benefits taxable in Canada?
If you pay the entire premium yourself, the benefits are tax-free. If your employer pays all or part of the premium, the benefits are taxable.
That is why two plans with the same monthly benefit can leave very different amounts in your pocket. Get tax advice for corporate or mixed arrangements.
Can a self-employed person buy disability insurance?
Yes, usually. Eligibility and the amount depend on your occupation, documented income, health and insurer rules.
Self-employed people have no employer plan or sick leave to fall back on, so the gap is usually larger. Business overhead expense coverage can also help keep the business running.
What about EI sickness benefits?
EI sickness benefits can pay up to 26 weeks at 55% of your earnings, to a maximum of $729 a week.
That helps in the short term, but it ends after 26 weeks and is capped, so it doesn't replace long-term disability coverage.
What happens to my coverage if I change jobs?
Group coverage usually ends when you leave the job or stop being eligible. An individual policy stays in force as long as you pay the premiums.
If you are planning to leave a job, apply for individual coverage while you are still healthy and employed.
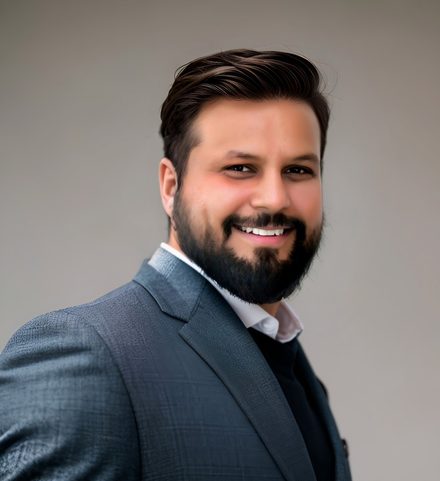
Written by Pankaj Bhatia, CHS, PFA
Insure In Canada Inc. · Mississauga and Cambridge, Ontario · Licensed in Ontario, Alberta, British Columbia, Manitoba, Saskatchewan, New Brunswick and Nova Scotia
Pankaj Bhatia is a financial advisor and director of Insure In Canada Inc. with 11 years of financial-services experience. He starts every disability review with the client's group booklet, because most surprises are in the definition, the offsets and the monthly maximum.
Call 647-640-2222 · WhatsApp · info@pankajbhatia.ca · About Pankaj
Sources and related pages
General education only, not legal, accounting or tax advice. Definitions, exclusions, benefit amounts and claim requirements are set by the specific insurance contract. Tax-sensitive arrangements should be reviewed with a professional.